Dear Editor,
President Irfaan Ali, Mr. Bharrat Jagdeo, and Dr Ashni Singh often present themselves as the nation’s most capable economic managers. After six years in office, however, that claim deserves scrutiny. The absence of effective public policy to combat the underlying pressures in our economy has produced a troubling reality: broad money has grown far beyond historical norms, and the cost-of-living consequences are being felt primarily by the ordinary Guyanese.
Of the three leaders, only Mr. Jagdeo is a trained economist, so I will address this matter to him directly, since I have no confidence in the economic competence of the other two. Economics teaches us that broad money growth has a direct relationship with the inflation that people actually experience. This reality exposes the inaccuracies of the figures published by the Guyanese Bureau of Statistics in conformance to the wishes of their political masters.
What Guyana is experiencing fits the pattern of “fiscal dominance,” where fiscal policy overwhelms monetary policy, compelling the central bank to accommodate ballooning deficits regardless of the inflationary consequences. As Nobel laureate Thomas Sargent observed, “High and persistent inflations are always and everywhere a fiscal phenomenon, in which the Central Bank is its accomplice”.
The data is instructive. Guyana’s broad money historically grew by roughly 10 to 13 percent annually and sometimes even lower. According to available figures, it rose by about 23 percent in 2023, 23 percent in 2024, and nearly 28 percent in 2025. At the end of June 2026, money supply stood at just below $1.46 Trillion and is set to surpass $1.6 Trillion by the end of 2026. This is up from $0.5 Trillion when Mr. Ali assumed stewardship of the Guyanese economy in August 2020 from President Granger. These facts demonstrate that the money supply has roughly tripled over the last six years, while the non-oil economy has grown by less than half that amount (see graph below).
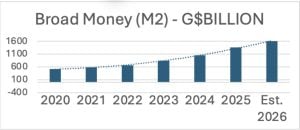
One must ask: where are the goods coming from to absorb this extra liquidity? Imports that are purchased with foreign currency. This evidence helps explain the persistent foreign exchange pressures that have become a regular feature of the Guyanese economy since 2023.
The experiences of Zimbabwe offer a cautionary parallel. There, quasi-fiscal operations and export surrender requirements drove an expansion in the creation of money that was not backed by productivity gains. This situation produced a vicious cycle of too much cash chasing too few goods. The Reserve Bank of Zimbabwe’s own experience demonstrates how poor monetary and fiscal coordination can accelerate broad money growth and inflict severe hardship on the population. Guyana is rapidly approaching this situation.
I therefore call on the political opposition and the President-in-waiting and Leader of the Opposition, Mr. Azruddin Mohamed, to ensure that their economic team is studying this issue and will write about it soon. As a party preparing for government, the WIN Team owes the nation a clear answer: what fiscal and monetary measures would they implement to bring immediate relief to the poor? This is how they will be properly measured if they are to gain respect.
In Guyana, the biggest losers remain our children, whose nutrition suffers as mothers buy cheaper; less nutritious food and raid savings to make ends meet.
I have not seen any particularly interesting writing on these matters from Mr. Mohamed or any of his leadership Team. It is time for them to step forward with substance, and stop running through the town in his nightgown, crying through the shadows: “Is Mr. Prem Narine in his bed? For now it’s midnight.”
Yours faithfully,
Surujdai Juglall


Discussion