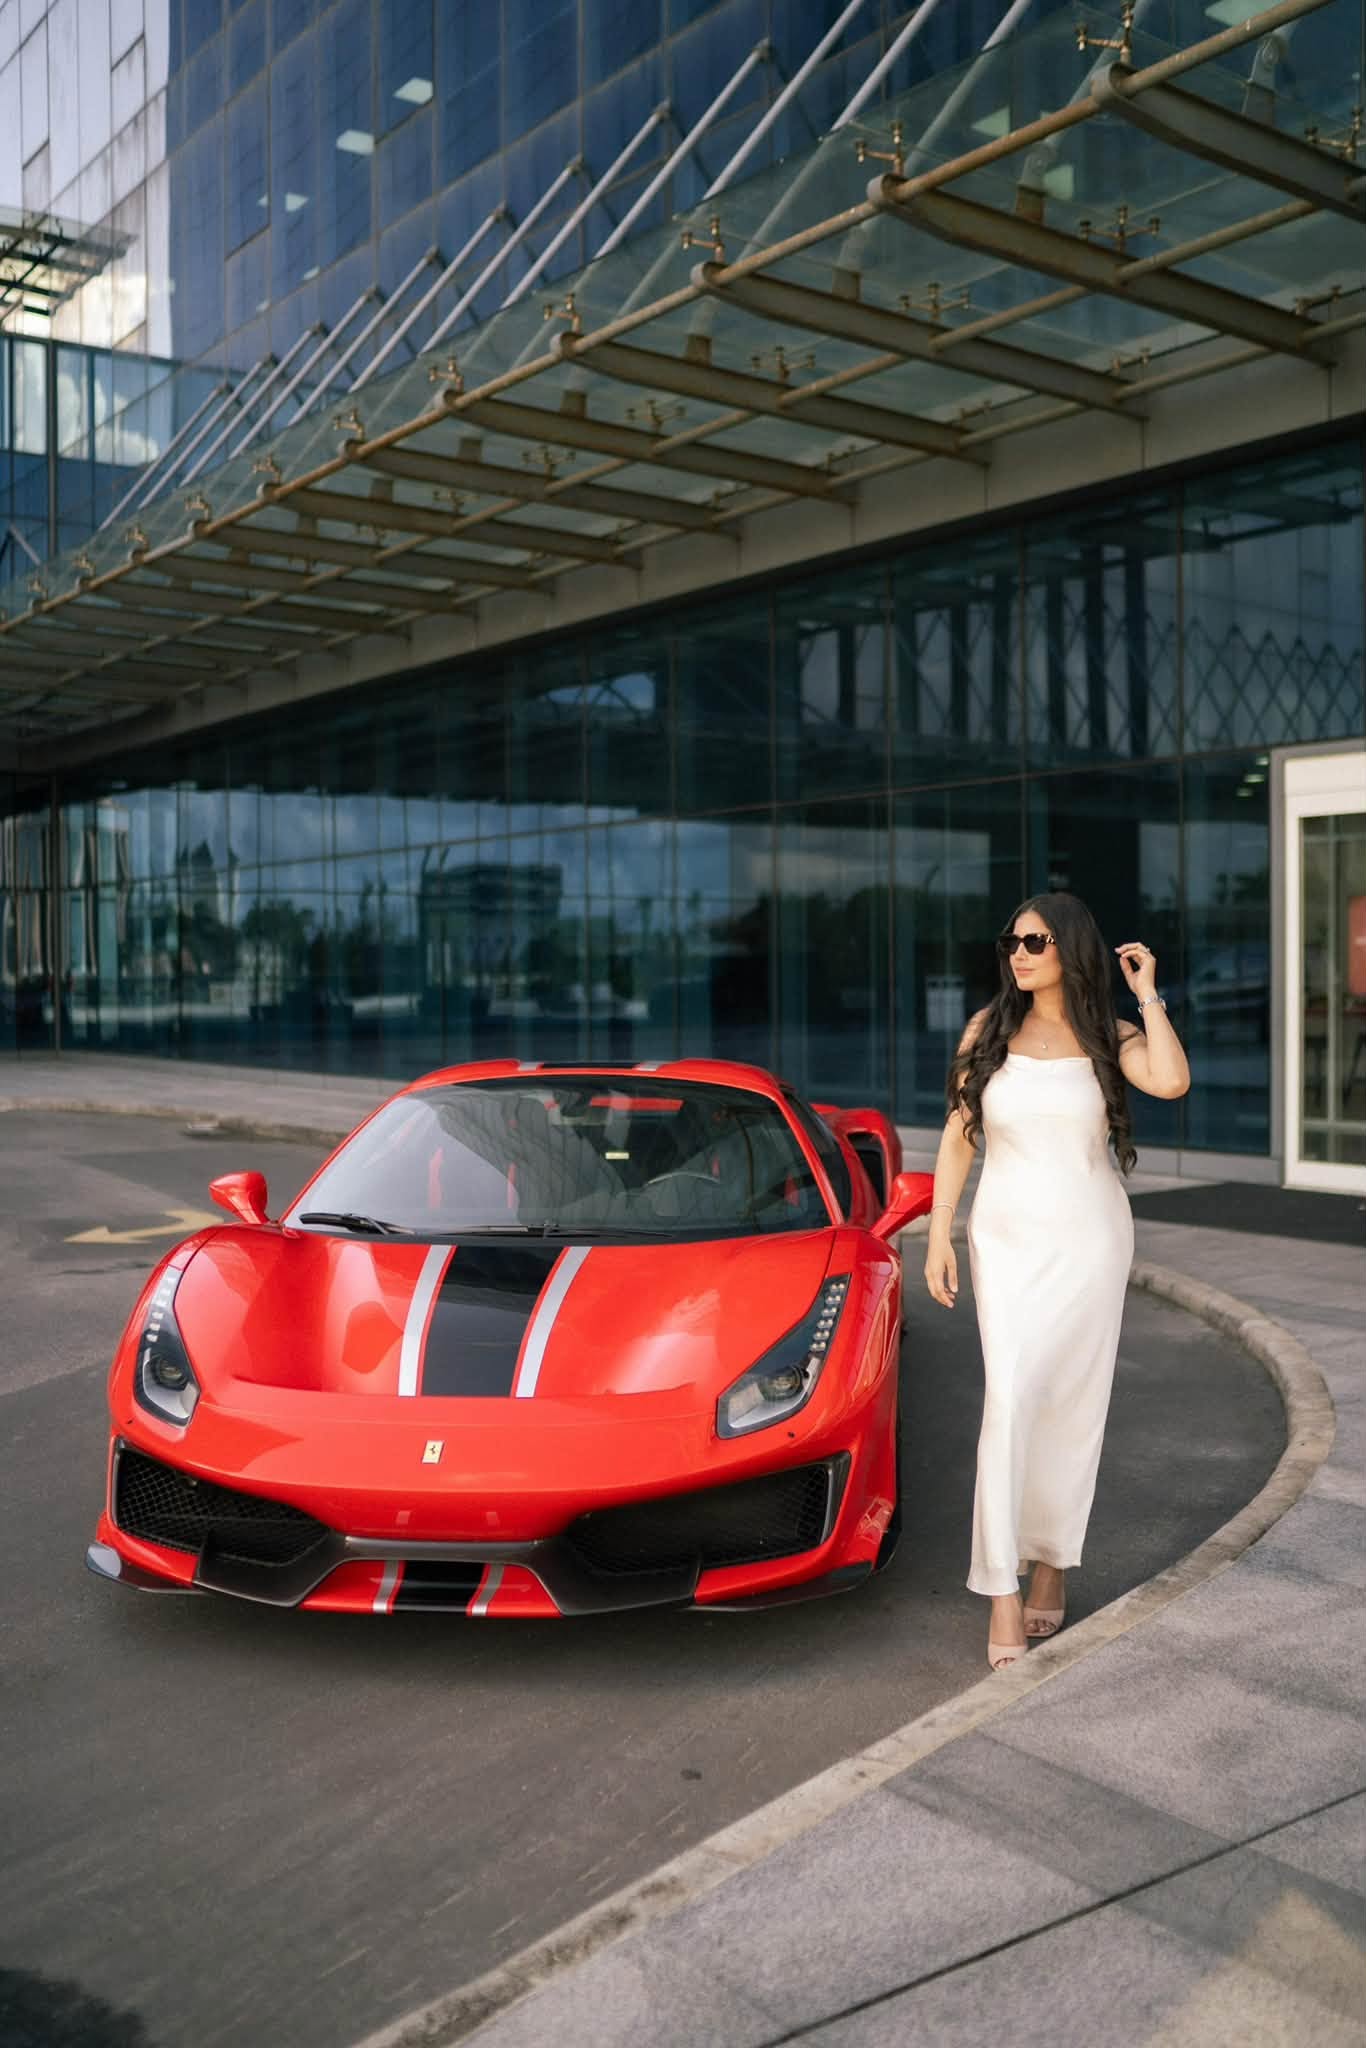
The Guyana Revenue Authority (GRA) has taken its fight over a $479.7 million tax assessment on a Ferrari 488 belonging to re-migrant Guyanese Hana Mohamed to the Court of Appeal, challenging a High Court decision which quashed the assessment and restrained the Authority from seizing the luxury vehicle.
The appeal was filed by the Commissioner General of the Revenue Authority and the Revenue Authority against Mohamed, following Justice Gino Persaud’s July 2, 2026 decision in which the High Court found that the Commissioner General had failed to lawfully consider and apply his discretion in relation to Mohamed’s reasons for her temporary absences from Guyana.
The High Court found that the Commissioner General’s failure was unreasonable, arbitrary, irrational, unfair and unlawful.
Justice Persaud consequently granted an order of certiorari quashing the Revenue Authority’s imposition of $479,743,489 in taxes in respect of Mohamed’s used 2020 Ferrari 488, registration PAD 5000, as communicated in the GRA’s March 2025 letters.
The court also quashed the GRA’s requirement for Mohamed to present or surrender the Ferrari to its Law Enforcement and Investigative Division and quashed the rescission of her tax exemption letters dated July 19, 2022 and January 6, 2023.
The matter was remitted to the Commissioner General for reconsideration, with the High Court directing that Mohamed’s reasons for her temporary absences from Guyana be fairly considered in determining whether she had breached the statutory residency conditions attached to her re-migrant tax exemption.
The Commissioner General was also directed to afford Mohamed a reasonable opportunity to make further written representations and provide documentary evidence, take into account legally relevant matters, disregard irrelevant matters and give reasons for any fresh decision.
The High Court further granted a permanent injunction restraining the Revenue Authority, its servants and agents from seizing or detaining the Ferrari or instituting forfeiture and condemnation proceedings based solely on the quashed decisions.
The Revenue Authority is now asking the Court of Appeal to overturn that judgment.
In its grounds of appeal, the GRA argues that Justice Persaud erred in law and fact when he quashed the $479.7 million tax assessment and found that Mohamed had established grounds for judicial review.
The Authority contends that the judge was wrong to find that the Commissioner General had a discretion to exercise in dealing with Mohamed’s alleged failure to comply with the terms of the re-migrant concession granted under Section 23 of the Customs Act.
The GRA is also challenging the High Court’s interpretation of the requirement for a person to be resident in Guyana for 183 days, including the court’s consideration of provisions of the Income Tax Act in interpreting the residency requirement under the Customs Act.
The Authority further argues that Mohamed had breached the terms of the concession and that the Commissioner General acted lawfully when he required her to show cause why the concession should not be set aside.
Another ground of appeal is that the letters setting out the terms of the concession effectively constituted a contract between the Revenue Authority and Mohamed, under which she received the re-migrant benefit on the basis that she complied with the stated conditions.
The GRA is also challenging the High Court’s treatment of Section 36 of the Customs Act and its finding concerning the Authority’s ability to seize the Ferrari and pursue forfeiture and condemnation proceedings.
The Authority maintains that it was entitled to rely on Section 209 of the Customs Act to seize or detain the vehicle following Mohamed’s failure to pay or secure the taxes demanded.
The Revenue Authority is asking the Court of Appeal to set aside and reverse Justice Persaud’s judgment, dismiss Mohamed’s judicial review application, discharge the injunction and award costs in its favour.
While the Revenue Authority seeks to overturn the High Court ruling, Mohamed has filed her own notice indicating that she intends to contend that part of the decision should be varied in her favour.
Her challenge concerns how any duties and taxes should be calculated if she is ultimately found to have breached the residency conditions attached to her re-migrant concession.
Mohamed argues that Justice Persaud erred in finding that Section 23(3)(d) of the Customs Act was inapplicable and that Section 36 applied to the breach.
She maintains that Section 23 specifically sets out the conditions relating to the vehicular re-migrant tax exemption scheme and the consequences of a breach.
Mohamed further argues that any duties payable should be assessed proportionately, by reference to the portion of the concessionary period remaining at the time of the alleged breach.
She also contends that the High Court should have determined the proper legal basis for calculating any duties and taxes before remitting the matter to the Commissioner General for reconsideration.


Discussion