
Amid sustained protest by opposition members, the National Assembly yesterday rushed through and passed the Guyana Development Bank Bill, paving the way for the establishment of a state-owned lending institution capitalised at $40 billion.
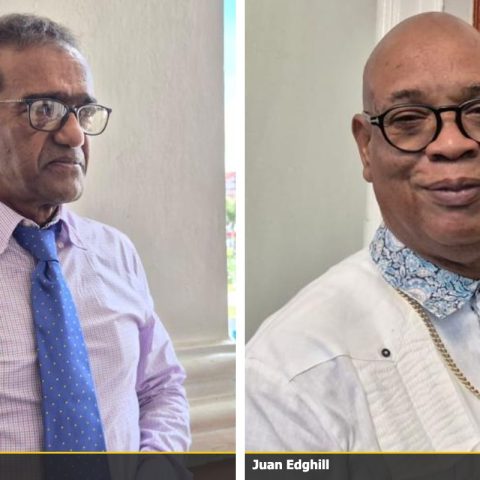
The bill was among four passed during the sitting as opposition MPs chanted and thumped their desks while repeatedly demanding the resignations of Minister of Public Works Juan Edghill and Minister of Public Utilities and Aviation Deodat Indar over the MV Barima tragedy.
“Who must go? Edghill and Indar,” they chanted as government MPs proceeded with the business of the Assembly, at times going directly in front of speakers holding up photographs of some of those who perished in one of Guyana’s worst tragedies.
Speaker Manzoor Nadir repeatedly called for order and cautioned opposition members. He also called the names of MPs listed to speak during the debate but, with the chanting continuing and no response forthcoming, quickly moved on to the other speakers.
Government members, including Minister of Agriculture Zulfikar Mustapha, spoke in support of the bill, which was subsequently read for a third time and passed.
The legislation was initially tabled on June 5 by Senior Minister in the Office of the President with responsibility for Finance Dr Ashni Singh. Its passage comes almost one year after President Irfaan Ali had announced plans to establish the bank to provide financing to small and medium-sized enterprises.
Ali had announced the proposed institution in July last year at the launch of a People’s Progressive Party/Civic campaign rally in Kitty. He said it would stimulate economic growth and offer zero-interest financing specifically to small and medium-sized businesses.
Under the legislation, the bank will begin with capital of $40 billion, subscribed and paid by the government in amounts and at times determined by the Finance Minister. The minister will also be permitted, by order and subject to a negative resolution of the National Assembly, to amend that amount.
The bank will be exempt from taxes on its profits and income. Its funding will include sums appropriated by Parliament, loan repayments, interest, other loan charges and any money or property that becomes payable to or vested in it in connection with its functions.
Individual borrowers and enterprises will initially be restricted to loans of no more than $3 million. Applicants will be required to provide the information, documents and statutory declarations prescribed or requested by the institution.
The Finance Minister will be able to amend the loan ceiling by order, subject to a negative resolution of the Assembly.
The bank will be empowered to take all necessary steps to recover money owed to it, including enforcing securities and guarantees given in support of loans.
It will not, however, be permitted to accept deposits from the public, engage in speculative trading or conduct business inconsistent with its development mandate.
The legislation establishes penalties for providing false or misleading information, obstructing the bank, falsifying or destroying its records, improperly disclosing confidential information and wilfully misusing its money, property or assets.
Anyone convicted summarily of an offence will face a fine of between $5 million and $10 million. Corporate bodies will be liable to the same range of fines.
Where a corporate offence was committed with the consent or connivance of a director, manager, secretary or similar officer, or resulted from that person’s neglect, the individual will also be deemed to have committed the offence and will be liable to the prescribed penalty.
The bank will be governed by a board comprising between five and nine directors. The Finance Minister will appoint its chairperson, deputy chairperson and other directors based on their qualifications and experience in finance, economics, banking and law.
Significantly, the institution will not be subject to the Financial Institutions Act. It will instead be governed by its own legislation and any orders or regulations issued under it.
The Ministry of Finance, shortly after the bill was tabled, said access to financing was central to the establishment, growth and success of businesses and the economic empowerment of individuals and households.



Discussion