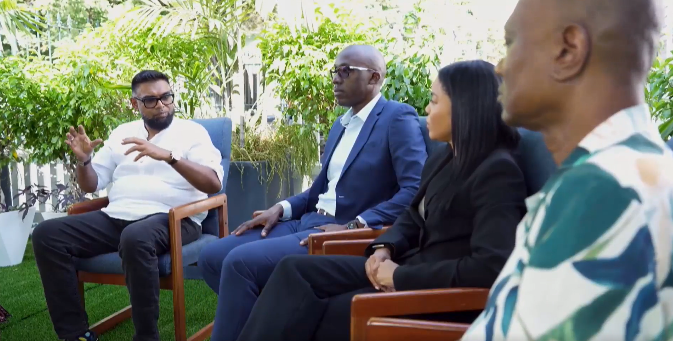
Persons selected for loans from the Guyana Development Bank will be publicly identified before receiving financing and members of the public will be allowed to raise objections, President Irfaan Ali said yesterday.
Ali disclosed the proposed accountability mechanism during a live discussion on the bank, which is scheduled to begin processing loan applications on October 5.
Participating were Republic Bank (Guyana) Limited Managing Director Dr Toussant Boyce; American Chamber of Commerce of Guyana President Iman Khan-Cummings; Caribbean Airlines Sales Executive for Guyana and Suriname Dion Inniss; Georgetown Chamber of Commerce and Industry President Kathy Smith; consultant Gina Arjoon; a former Scotiabank Guyana branch head Abu Zaman; and businessman Clinton Urling.
Ali said publishing the names would allow communities to identify possible attempts by related persons or established business owners to dominate the programme.
“The bank would also have a very fair system of publicising [the names] because that’s what we want—the community to know,” he said.
According to Ali, a database of beneficiaries will be established and the public could be given one or two weeks to raise concerns. He gave as an example in another matter of residents recognising that four proposed beneficiaries were brothers.
The announcement follows concerns from opposition figures and commentators that the state-owned bank could be politicised or used to favour supporters of the governing PPP/C.
Ali said established contractors and business owners should not place themselves ahead of vulnerable people for whom the programme was intended. Financing would initially be distributed as widely as possible, but collateral-free lending did not mean applications would escape scrutiny.
“This is not a grant,” he repeatedly told the panel. “This is your opportunity to earn. This is your opportunity to pay back. This is an opportunity to build your credit.”
The institution is intended to offer interest-free, collateral-free loans of up to $3 million to small and medium-sized businesses. Young people, women, persons living with disabilities and other prospective entrepreneurs have been identified among its intended beneficiaries.
Smith asked whether public servants who also operated businesses would qualify. She said public-sector employees were among women who had enquired about an initiative to provide shade houses.
Ali said public- and private sector employees could apply, although salaried workers who were not considered low-income applicants might have to await a later financing round.
“The first issuance is to go to ideas, creativity, innovation [and] vulnerability,” he said.
Applications would be assessed through the bank’s system and no category would automatically receive priority, he added.
Ali said coaching and mentorship would be compulsory. Applicants would not merely submit a form and automatically receive $3 million. Specialists would assess proposals, refine ideas and connect borrowers with extension services, established companies and commercial banks.
Khan-Cummings said capital alone would not create sustainable businesses and emphasised mentorship, training, technical assistance and help with preparing proposals.
Development Bank desks are to be placed in commercial banks countrywide, while an electronic platform is being developed for applicants, including those in hinterland and riverine communities. The platform would help small operators prepare financial statements and allow technical personnel to monitor their businesses.
Ali said the government had received hundreds of expressions of interest and would conduct public education and countrywide outreaches before the launch.
Arjoon said she had visited approximately five regions since the bank was announced and had encountered significant interest from small operators.
Multiplier
Ali said successful businesses could create a multiplier effect through employment and increased purchases of goods and services. He suggested that the initial investment could generate economic activity several times its value.
Arjoon also observed that much of the discussion had focused on industries outside oil and gas. She said the bank could allow ordinary Guyanese to participate in other sectors, but borrowers would have to work to make their businesses successful.
The President placed heavy emphasis on consortiums, arguing that individual applicants could be grouped into larger, more viable ventures. Small poultry farmers, for example, could operate collectively at an appropriately equipped location rather than maintaining numerous backyard pens.
Urling said a $3 million New Building Society loan in 2000 provided the foundation for his business. It enabled him to acquire a capital asset, improve the operation and later approach larger commercial banks.
He said the Development Bank could similarly allow entrepreneurs to turn ideas into viable businesses. Urling also described a consortium formed approximately three years ago to pursue opportunities in the food and oil and gas sectors. Although its members hardly knew each other initially, he said, it had become successful and was considering further expansion.
Boyce said Republic Bank was prepared to finance consortiums comprising producers, processors, logistics operators and suppliers. He also questioned how the bank would ensure nationwide access and fairness, particularly for applicants outside the coast.
Inniss said the initiative could unlock the entrepreneurial potential of Guyanese, particularly young people and single mothers. He asked how it would support Guyanese-owned businesses in agriculture, agro-processing, community-based tourism and information technology.
Responding, Ali suggested that locally produced snacks and juices could be packaged for use aboard Caribbean Airlines flights. Products made by Indigenous women could be marketed with information about their communities, thereby linking small producers to a larger company and wider market.
Zaman was introduced as a former head of Scotiabank Guyana who remained involved in community activities.
Ali said the bank would focus on productive activities, including agriculture, agro-processing, tourism, information technology, transportation, creative industries and small-scale manufacturing, rather than allowing applicants to concentrate on identical ventures such as taxis.
Air-conditioned boat service
Among the proposals discussed were an air-conditioned boat service between Port Kaituma and Charity, an electric community bus service, shade houses, food trucks, poultry and dairy projects, vacuum-packed breadfruit and the supply of local snacks and beverages to airlines.
The Guyana Development Bank Act is scheduled to come into operation on October 5. The government is providing an initial US$100 million—approximately $20 billion—representing half of the bank’s authorised capital of $40 billion.
The bank will not be governed by the Financial Institutions Act and cannot accept public deposits. The Finance Minister will appoint its entire board, including its chairperson and deputy chairperson.
Chartered accountant and attorney Christopher Ram previously told Kiskadee Watch that the exemption from the Financial Institutions Act removed important prudential safeguards. APNU parliamentarian Terrence Campbell has warned that ministerial appointment of the entire board could lead to politicisation.
APNU Leader Aubrey Norton has said that his party supports the concept but fears the bank could favour PPP/C supporters. APNU parliamentarian Sharma Solomon has questioned whether entrepreneurs in all ten regions will have equitable access.
In October 2025, Stabroek News reported that the government had initially proposed US$200 million in seed financing. Budget 2026 subsequently allocated US$100 million for the initial injection and proposed a co-investment model under which qualifying businesses could access up to an additional $7 million from participating commercial banks at preferential rates.


Discussion